
Why Digital Payments Are Entering a New Regulatory Phase in India

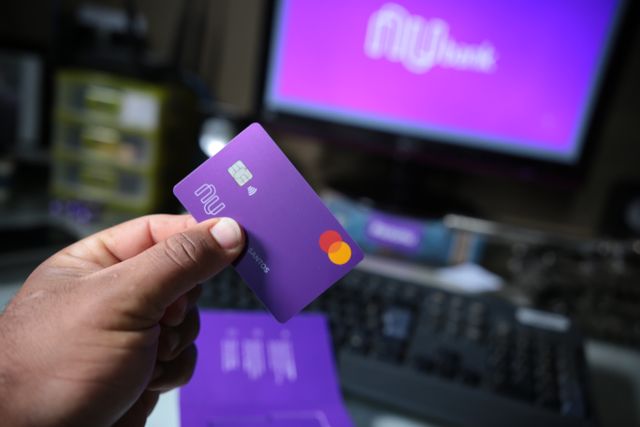

India’s digital payment ecosystem has transformed the way individuals, businesses, and public institutions exchange money. From scanning a QR code at a neighbourhood shop to paying utility bills through mobile applications, digital transactions have become part of everyday economic activity. The expansion of the Unified Payments Interface (UPI), mobile banking, digital wallets, payment gateways, and online merchant services has reduced dependence on cash and made electronic payments accessible to millions of people.
However, the rapid expansion of digital payments has also created new regulatory challenges. As transaction volumes grow and payment services become increasingly interconnected, regulators must address fraud, cybersecurity, consumer complaints, data protection, operational disruptions, and the responsibilities of companies operating across the payment chain. The challenge is no longer simply to encourage digital adoption. It is to ensure that the system remains secure, reliable, competitive, and trustworthy as it grows.
India is therefore entering a more demanding phase of digital payment regulation, in which consumer protection, risk management, technological resilience, and accountability are becoming increasingly important. This does not mean that one single regulatory change defines the entire sector. Rather, the shift reflects a broader evolution in how payment systems are supervised and how financial institutions, technology companies, merchants, and users are expected to manage digital financial risks.
How Digital Payments Became Essential to India’s Economy
India’s digital payment growth has been supported by improvements in smartphone access, affordable mobile internet, digital banking, QR-code acceptance, and public digital infrastructure. UPI has been particularly influential because it allows users to transfer money between participating bank accounts through supported applications without requiring the recipient to use the same payment app. Its interoperable design has helped digital payments expand beyond traditional online shopping into everyday transactions.
Small merchants, street vendors, local service providers, and independent professionals can now accept electronic payments with relatively simple infrastructure. Consumers can divide bills, transfer money to family members, pay businesses, and complete transactions without carrying cash. Companies benefit from faster payment confirmation and more convenient reconciliation, while public institutions can use digital channels to distribute benefits and collect certain payments.
Yet the scale of this transformation changes the nature of regulatory responsibility. A payment failure can affect thousands of merchants and customers at once. A sophisticated fraud campaign can exploit weaknesses across multiple applications and institutions. An outage at a critical service provider can interrupt transactions across a wide network. The more deeply digital payments become embedded in economic activity, the more important it becomes to establish clear standards for security, continuity, dispute resolution, and accountability.
The Role of the Reserve Bank of India
The Reserve Bank of India (RBI) is a central institution in India’s payment regulation framework. It oversees relevant payment systems and establishes requirements intended to promote safety, efficiency, and public confidence. Its regulatory responsibilities extend across areas such as payment system authorisation, operational safeguards, customer protection, security expectations, and the conduct of regulated entities.
The regulatory environment also involves the National Payments Corporation of India (NPCI), which operates important retail payment infrastructure including UPI, as well as banks, payment aggregators, payment gateways, and other service providers. Their responsibilities differ according to their roles, legal status, and the applicable regulatory framework.
As digital payments become more complex, supervision must address not only the transaction itself but also the institutions and technologies supporting it. A consumer may experience a payment through a single mobile application, even though the transaction depends on several interconnected systems. Regulators therefore need visibility into how participants manage risks, respond to incidents, protect customers, and maintain service continuity.
This makes regulation a continuous process rather than a one-time approval. Rules must respond to changing business models, new fraud techniques, emerging technologies, and the increasing importance of digital payments in the wider financial system.
Fraud Prevention Is Becoming a Major Regulatory Priority
Digital payment fraud is one of the most visible reasons for strengthening safeguards. Fraudsters may use phishing messages, fake customer-care numbers, deceptive links, screen-sharing applications, impersonation, fraudulent QR codes, or social engineering to persuade users to reveal credentials or authorise transactions. Some scams exploit the mistaken belief that entering a UPI PIN is necessary to receive money, when a PIN is generally used to authorise a payment or another specifically supported action.
The problem is not limited to individual mistakes. Criminal networks can use stolen identities, compromised accounts, mule accounts, and coordinated transaction patterns to move funds through multiple channels. Fraud can also exploit gaps in the way financial institutions share risk signals or investigate suspicious activity.
Regulatory responses increasingly need to combine prevention, detection, and recovery. Financial institutions may use transaction monitoring, behavioural analytics, device-related signals, and risk-based authentication to identify potentially suspicious activity. Such systems can help detect unusual patterns, but they must be designed carefully to avoid blocking legitimate customers unnecessarily.
Banks and payment providers also need clear procedures for handling complaints, investigating disputed transactions, communicating with customers, and cooperating with relevant authorities. Customers should be encouraged to report unauthorised transactions quickly through official channels. The exact outcome of a complaint depends on the circumstances and the applicable rules, so digital payment users should not assume that every fraudulent transfer will automatically be reversed.
Consumer Protection and the Right to Clear Information
As payment services become easier to use, consumers may not always understand who is responsible when a transaction fails or a complaint remains unresolved. A payment may involve the user’s bank, the recipient’s bank, a payment application, a merchant, and the underlying payment infrastructure. This complexity can make it difficult to identify the correct organisation for assistance.
Regulatory oversight must therefore promote clear communication about payment status, fees where applicable, complaint procedures, and the responsibilities of different service providers. Consumers need accessible information explaining what to do when money is debited but the recipient does not receive it, when a transaction remains pending, or when an unauthorised payment appears in their account.
The quality of dispute resolution is particularly important because digital payments operate on the expectation of speed. Users who complete a transaction within seconds may reasonably expect support systems to respond promptly when something goes wrong. However, investigation and settlement may require coordination between multiple institutions, depending on the type of failure.
An effective consumer protection framework should make the complaint process understandable and traceable. Customers should be able to obtain a reference number, receive updates, and escalate unresolved matters through the relevant bank or payment provider and, where applicable, the appropriate regulatory grievance mechanism. Trust depends not only on preventing problems but also on resolving them fairly when they occur.
Data Privacy and the Security of Financial Information
Digital payments generate sensitive information about financial activity, transaction relationships, purchasing behaviour, and service usage. When combined with other data, these records may reveal patterns in a person’s routine, preferences, and economic circumstances. Protecting this information is therefore an important part of responsible payment regulation.
Payment service providers need to collect and process information for legitimate purposes while following the legal and regulatory requirements applicable to their operations. Security controls, access restrictions, appropriate retention practices, and incident-response procedures help reduce the risk of unauthorised access or misuse. Data handling requirements may vary depending on the entity, the information involved, and the applicable rules.
India’s regulatory approach also includes requirements relating to payment data storage. RBI directions issued in 2018 established data-storage requirements for payment system providers within their scope. Such requirements are distinct from the broader question of how personal data may be collected, shared, retained, or processed under applicable privacy law.
As payment services introduce more sophisticated fraud detection and personalisation systems, regulators face the challenge of balancing effective risk management with privacy. Collecting more information may improve some forms of monitoring, but it also creates additional responsibilities. A secure digital payment ecosystem should not treat every available piece of consumer data as automatically necessary.
Cybersecurity and Operational Resilience
A digital payment system must do more than process transactions quickly. It must also remain reliable when networks fail, software develops vulnerabilities, cyberattacks occur, or a third-party service experiences an outage. Because payment infrastructure supports everyday commerce, interruptions can have immediate consequences for households and businesses.
Cybersecurity risks include credential theft, malware, account takeover, unauthorised access, denial-of-service attacks, and vulnerabilities in software or connected systems. Payment providers may also depend on cloud services, telecommunications networks, technology vendors, and external processors. Weaknesses in one part of this chain can affect services elsewhere.
Regulation is consequently concerned with operational resilience as well as fraud prevention. Relevant safeguards can include access controls, secure software development, vulnerability management, system monitoring, backup arrangements, incident reporting, and recovery planning. Financial institutions and payment operators must understand how their critical services would continue operating during a disruption and how quickly essential functions could be restored.
Resilience also requires regular testing. A written disaster-recovery plan is not sufficient if it has never been tested under realistic conditions. Institutions need to evaluate whether their systems can handle sudden transaction surges, recover from technical failures, and communicate effectively with customers during service interruptions. The objective is to reduce the likelihood that a single technical problem will produce widespread disruption.
The Regulation of Payment Aggregators and Fintech Companies
India’s payment ecosystem includes a wide range of participants beyond traditional banks. Payment aggregators help merchants accept payments through different methods, while payment gateways provide technology that facilitates payment processing. Fintech companies may offer user interfaces, payment services, merchant tools, or other products connected to regulated financial infrastructure.
This diversity encourages innovation, but it also raises questions about responsibility. Consumers may interact mainly with a technology brand even when a bank or another regulated institution performs critical parts of the transaction. Merchants may rely on external payment providers without having a complete understanding of the operational and compliance risks involved.
Regulatory requirements for payment aggregators, including authorisation and relevant security or governance obligations, help establish minimum expectations for entities within the framework. Requirements depend on the particular activity and the rules applicable to the provider. Not every fintech company is regulated in the same way, and not every company offering a payment-related service performs the same legal function.
The broader direction is toward clearer responsibility across the payment chain. Providers need to understand which obligations apply to them, maintain appropriate controls, and avoid gaps in customer support or security simply because another organisation participates in the transaction. Well-designed regulation can support innovation by establishing predictable standards instead of leaving essential safeguards to voluntary practices alone.
The Impact on Small Businesses and Local Merchants
Small businesses have benefited considerably from digital payment acceptance. QR codes and mobile-based tools allow many merchants to accept electronic payments without investing in traditional card terminals. Digital transaction records can also support accounting, help merchants understand sales patterns, and reduce the burden of handling cash.
However, small businesses may have limited capacity to assess service-provider reliability, understand changing compliance requirements, or manage disputes. A payment outage during a busy trading period can affect sales, while delayed settlements or unclear charges can create cash-flow difficulties. Fraudulent payment confirmations and fake screenshots can also expose merchants to losses if they release goods without verifying the actual transaction.
A more mature regulatory environment should consider these practical realities. Payment providers need to communicate terms clearly, offer accessible support, and explain how merchants can verify payments and report problems. Regulators and industry participants can also improve awareness through practical guidance designed for small businesses rather than relying exclusively on technical documentation.
Compliance should be proportionate to the nature and scale of the activity while maintaining essential protections. If regulatory expectations become difficult to understand or disproportionately expensive to meet, smaller firms may struggle to participate. The objective should be a safer ecosystem that remains accessible to legitimate businesses of different sizes.
Financial Inclusion and the Risk of Digital Exclusion
Digital payments can reduce geographical barriers and make financial transactions more convenient for people who previously depended heavily on cash. Yet access to digital payment services is not uniform. Some users have limited internet connectivity, older devices, low digital literacy, accessibility requirements, or difficulty navigating applications in their preferred language.
A regulatory framework focused only on online efficiency may overlook these barriers. If a payment application is difficult to use or a fraud-prevention system repeatedly blocks legitimate transactions, the people who need accessible services most may be disproportionately affected. Excessively complicated verification procedures can also discourage participation, even when they are intended to reduce fraud.
Regulators and payment providers should therefore consider usability, accessibility, language support, and the availability of alternative channels. Consumers need practical ways to report problems and understand their rights without requiring advanced technical knowledge. Digital services should be designed so that security measures protect users without creating unnecessary obstacles to legitimate transactions.
Financial inclusion also depends on trust. People are more likely to use digital payment tools when they understand how the systems work, know how to seek help, and believe that mistakes or fraud will be handled fairly. Consumer education must therefore complement technical controls and formal regulation.
What the New Regulatory Phase Means for Innovation
Stronger regulation is sometimes presented as a barrier to fintech innovation. In practice, the relationship is more complicated. Unclear rules can make it difficult for businesses to plan, while weak safeguards can undermine consumer confidence and create systemic risks. Predictable and proportionate regulation can provide a stable environment in which responsible innovation is more likely to succeed.
Artificial intelligence, real-time risk analysis, tokenisation, biometric technologies, and new forms of digital financial infrastructure may influence the next generation of payment services. These developments can improve convenience or security in particular contexts, but each introduces questions about reliability, privacy, accountability, and the consequences of failure.
Regulators must be able to evaluate new business models without assuming that every innovation is inherently beneficial or inherently dangerous. Controlled testing, transparent risk assessments, consultation with industry participants, and clear compliance expectations can help authorities understand emerging technologies before they become widely embedded in critical payment systems.
At the same time, regulation must remain adaptable. Rules designed for one technology may not address risks created by another. Effective oversight requires continuous monitoring, technical expertise, cooperation among institutions, and the ability to update requirements as evidence and operating conditions change.
Conclusion: Building Trust Beyond Transaction Speed
India’s digital payment ecosystem is moving into a phase in which security, resilience, consumer protection, privacy, and accountability are becoming as important as rapid adoption. The growth of UPI and other electronic payment channels has expanded access to convenient transactions, but it has also increased the importance of protecting users and maintaining reliable infrastructure.
The Reserve Bank of India, payment system operators, banks, fintech companies, merchants, and consumers all have roles in maintaining the integrity of the ecosystem. Clear responsibilities, proportionate safeguards, effective complaint handling, robust cybersecurity, and informed users can help reduce risks without undermining the convenience that made digital payments popular.
The future of digital payments will not be determined by transaction volumes alone. It will depend on whether people and businesses can use these services with confidence, whether failures are addressed fairly, and whether innovation develops within a framework of responsible oversight. India’s next regulatory phase is therefore not simply about adding more rules. It is about ensuring that the country’s digital payment infrastructure remains trustworthy as it becomes an even more important part of everyday economic life.
Online Internship with Certificate
You may be interested
AI as a Government Tool: Where Real-Time Algorithms Are Already Entering Public Administration
Anshika Jain - Oct 13, 2026Artificial intelligence is gradually changing how governments collect information, deliver public services, monitor infrastructure, and respond to emerging problems. Traditionally, public administration has relied on manual reporting,…
When Students Protest: What Happens After a Campus Administration Faces Public Pressure?
Anshika Jain - Oct 13, 2026Universities and colleges are expected to provide students with an environment where learning, critical thinking, and open discussion can flourish. However, when students believe that their concerns…
Why Collectors Are Paying Millions for Pieces of Literary History
Anshika Jain - Oct 13, 2026Books are traditionally valued for the knowledge, imagination, and ideas they contain. However, for some collectors, a book can represent far more than its written contents. An…
Most from this category
Celebrity Influence in Advertising: Can Star Power Change Consumer Behaviour?
Anshika Jain - Oct 13, 2026
Asian Games 2026: Why India’s Women Athletes Are at the Centre of the Competition
Anshika Jain - Oct 13, 2026
What Students Will Learn From the New NCERT Governance and Public Policy Chapter
Anshika Jain - Oct 08, 2026
The New Era of Drone Warfare: How Technology Is Changing Modern Conflicts
Anshika Jain - Oct 08, 2026
Celebrity Influence in Advertising: Can Star Power Change Consumer Behaviour?
Anshika Jain - Oct 13, 2026Asian Games 2026: Why India’s Women Athletes Are at the Centre of the Competition
Anshika Jain - Oct 13, 2026What Students Will Learn From the New NCERT Governance and Public Policy Chapter
Anshika Jain - Oct 08, 2026