
Digital Payments and Small Shops: How Technology Is Changing Local Businesses


Digital payments are transforming the way small shops and local businesses operate. From neighborhood grocery stores and street vendors to salons, pharmacies, cafés, and repair shops, businesses that once depended almost entirely on cash are increasingly accepting payments through mobile applications, QR codes, cards, and internet banking. This change is not simply about replacing physical currency with digital transactions. It is influencing customer experiences, business operations, financial management, marketing, and long-term growth.
In many communities, small businesses play an important role in supporting local employment and meeting everyday consumer needs. Traditionally, shopkeepers managed sales through cash registers, handwritten records, and personal relationships with customers. Although these methods remain relevant, digital tools are helping business owners manage transactions more efficiently and respond to changing customer expectations. Consumers now often prefer quick, convenient, and traceable payment options, particularly when they do not have sufficient cash available.
The growth of digital payments has created new opportunities for small businesses, but it has also introduced challenges involving transaction charges, cybersecurity, technical problems, digital literacy, and financial management. Understanding these changes can help shopkeepers use technology responsibly while preserving the trust and personal relationships that make local businesses valuable.
The Shift from Cash to Digital Payments
For decades, cash was the primary payment method for many small shops. Customers carried physical currency, and shopkeepers counted money manually, maintained cash balances, and stored daily earnings. Cash transactions were familiar and straightforward, but they could also create difficulties. Businesses had to manage change, protect physical money, identify counterfeit notes, and maintain accurate records of daily sales.
Digital payments have introduced an alternative. Customers can scan a QR code, enter a mobile number, use a card, or transfer money through a banking application. In India, mobile-based payment systems have become increasingly common across urban and rural markets. Even small roadside stalls and independent vendors may display QR codes that allow customers to pay directly from their smartphones.
This transition is supported by wider access to smartphones, affordable internet connectivity, digital banking services, and payment applications. For many customers, digital payments offer convenience because they eliminate the need to carry exact cash. For business owners, they can reduce the effort associated with handling physical money and provide transaction records that support financial tracking.
However, digital payments are not replacing cash in every situation. Some customers may have limited internet access, low digital confidence, or concerns about privacy and fraud. Power cuts, poor network connectivity, device problems, and payment failures can also interrupt transactions. Therefore, many small businesses continue to use a combination of cash and digital payment methods.
How QR Codes Are Supporting Small Businesses
Affordable Payment Infrastructure
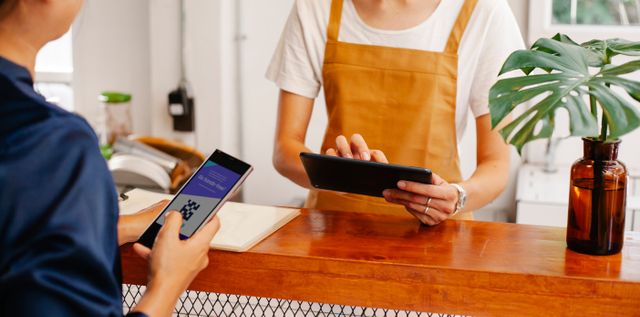
One of the most visible changes in local markets is the widespread use of QR codes. A shopkeeper can display a printed QR code near the counter, allowing customers to scan it with a compatible payment application. This approach can be more affordable and accessible than purchasing a traditional card payment machine.
QR-based payments are particularly useful for businesses with small transaction values. Customers can pay for groceries, tea, snacks, stationery, transportation, and other everyday products without exchanging cash. The process is generally quick, and transaction notifications can help shopkeepers confirm whether a payment has been received.
For small business owners, the main benefit is that digital payment acceptance does not always require a complicated setup. Depending on the provider, merchants may be able to register using a mobile phone and bank account. However, business owners should carefully review provider terms, settlement timelines, applicable charges, and customer-support options before selecting a service.
Improved Customer Convenience
Customers increasingly expect businesses to offer flexible payment choices. A shopper may not have cash available but may still be able to complete a purchase through a mobile payment application. This convenience can reduce abandoned purchases and make transactions easier for both parties.
Digital payments may also support faster service during busy periods. Instead of counting notes and searching for change, customers can complete transactions electronically. In crowded shops, cafés, and food stalls, this can help reduce waiting time, although transaction confirmation must still be checked carefully.
Convenience can strengthen customer satisfaction, but it should not replace reliable service. Customers are more likely to return when digital payment options are combined with fair pricing, product quality, transparent billing, and respectful communication.
Digital Payments and Business Record-Keeping
Moving Beyond Handwritten Accounts
Many small businesses traditionally record sales in notebooks or rely on memory. While this method may work for a small number of daily transactions, it becomes more difficult as the business grows. Digital payments can create electronic transaction histories that help shopkeepers review incoming payments and compare them with sales records.
Digital records can support daily reconciliation, allowing a business owner to compare the amount sold with the amount received. They may also make it easier to identify missing payments, repeated transactions, and differences between expected and actual revenue.
However, payment records should not automatically be treated as complete accounting records. A transaction statement may show money received, but it may not include inventory costs, operating expenses, credit sales, refunds, or cash payments. Small businesses should maintain organized records that combine digital transactions with other financial information.
Supporting Financial Planning
Accurate records can help business owners understand their sales patterns. By reviewing transaction data, a shopkeeper may identify busy days, popular products, seasonal demand, and periods of low activity. This information can support decisions about purchasing inventory, adjusting business hours, or planning promotions.
For example, a small grocery store may notice that digital transactions increase during weekends, while a stationery shop may experience higher demand during examination periods. These observations can help business owners prepare stock and manage cash flow more effectively.
Digital information becomes valuable when it is reviewed regularly and interpreted correctly. Business owners should avoid making decisions based only on transaction volume because high sales do not necessarily mean high profits. Expenses, supplier payments, discounts, damaged goods, and unpaid credit must also be considered.
Expanding Access to Financial Services
Digital payments can create a connection between small businesses and formal financial services. When merchants receive payments through bank-linked systems, they may develop more organized financial records and become familiar with digital banking tools. Depending on eligibility and local financial regulations, transaction histories may support certain financial service applications, although approval is never guaranteed.
Formal financial records can be useful when businesses seek working capital, equipment financing, insurance, or other services. However, shopkeepers should understand that lenders evaluate multiple factors, including repayment capacity, business income, existing liabilities, and documentation.
Digital payment adoption should therefore be viewed as one part of broader financial development rather than an automatic pathway to credit. Business owners should compare loan terms carefully, understand interest rates and fees, and avoid unverified lenders promising instant approval.
The Role of Digital Payments in Customer Relationships
Building Transactional Transparency
Digital payments can improve transparency by providing transaction confirmations and records. Customers may be able to review their payment history, while merchants can verify amounts received. This can reduce certain misunderstandings about payment amounts or change.
Nevertheless, digital records do not eliminate the need for clear communication. A customer may receive a payment notification while the merchant’s system has not yet confirmed the transaction. Shopkeepers should verify the actual payment status rather than relying only on screenshots or customer statements.
Clear refund policies are also important. If a customer is charged twice or a payment is deducted without the order being completed, the business should explain the next steps and cooperate with the payment provider where necessary. Responsible handling of payment problems can strengthen trust.
Encouraging Repeat Purchases
Some digital payment services offer transaction histories, loyalty features, digital receipts, or promotional tools. These features may help businesses communicate with customers and encourage repeat purchases, provided that customer information is handled responsibly.
A local café, for instance, may use digital receipts and a simple loyalty system to recognize regular customers. A small clothing store may share information about new arrivals through an approved communication channel. Such strategies can support customer engagement without requiring the business to invest in expensive marketing infrastructure.
Businesses should avoid sending unwanted promotional messages or collecting personal information without a legitimate purpose. Customer trust can be damaged when contact details are misused or shared without permission.
Digital Marketing and Local Business Growth
Digital payment adoption is often connected to a broader shift toward online visibility. Small shops are increasingly using map listings, social media pages, messaging applications, and digital catalogues to attract customers. A business that accepts digital payments may also promote its services online, making it easier for new customers to discover the shop.
A neighborhood bakery, for example, can display its products through social media, accept advance orders through a messaging platform, and collect payments digitally. A home-based clothing seller may share product photographs, respond to customer inquiries, and use digital payments to complete orders.
Technology can help local businesses reach customers beyond their immediate surroundings, but online visibility also requires accurate information. Businesses should provide correct opening hours, contact details, product descriptions, and pricing. Misleading advertisements or unclear terms can create disputes and reduce customer confidence.
Digital marketing should be based on realistic promises and consistent service. A strong online presence cannot compensate for poor product quality, delayed delivery, or unresponsive customer support.
Challenges Faced by Small Shopkeepers
Digital Literacy and Training
Not every shopkeeper has the same level of comfort with digital tools. Some business owners may be unfamiliar with application settings, transaction histories, refunds, cybersecurity, or account recovery. Older merchants and individuals with limited formal technology training may find digital systems difficult to manage.
Training and simple user interfaces can help reduce these challenges. Payment providers, financial institutions, trade associations, and local organizations can support small businesses by offering practical guidance in local languages. Training should explain not only how to accept payments but also how to identify fraudulent transactions and protect account information.
Digital inclusion requires ongoing support. A business owner should be able to access customer assistance when a transaction fails, an account is locked, or a payment is disputed.
Internet and Electricity Dependence
Digital payment systems depend on technological infrastructure. Weak mobile networks, device battery problems, server interruptions, and electricity shortages can prevent transactions from being completed. These issues may be especially challenging for businesses operating in areas with inconsistent connectivity.
Small businesses should maintain practical alternatives, including the ability to accept cash when appropriate. Merchants should also avoid pressuring customers to make repeated payments when the status of the first transaction is unclear. Checking transaction histories and contacting the payment provider can help prevent duplicate payments.
Technology is most useful when it is supported by contingency planning. Businesses should understand how to respond when digital systems become temporarily unavailable.
Transaction Costs and Settlement Delays
Depending on the payment method and provider, merchants may face charges, settlement conditions, equipment expenses, or service limitations. These costs can affect businesses that operate with narrow profit margins. Shopkeepers should carefully review the pricing structure of payment services and understand whether fees apply to specific transaction types.
Settlement timing is another important consideration. The time at which a customer completes a payment may not always be the same as the time the merchant can use the funds. Business owners should monitor bank statements and understand the provider’s settlement process.
Comparing available services and maintaining clear financial records can help merchants make informed decisions about payment systems.
Cybersecurity Risks for Local Businesses
Digital payments create convenience but also expose merchants to new forms of fraud. Criminals may send fake payment screenshots, impersonate bank representatives, share fraudulent customer-support numbers, or persuade shopkeepers to scan malicious QR codes. Some scammers claim that a merchant must enter a PIN or approve a payment to receive money.
A key safety principle is that receiving money generally does not require a merchant to enter a banking PIN or approve an unknown payment request. Shopkeepers should verify incoming payments through their official payment application or bank account rather than relying solely on sounds, screenshots, or messages.
Merchants should use strong passwords, enable additional security controls where available, keep their devices updated, and avoid sharing OTPs or account credentials. They should also limit access to payment applications and ensure that employees understand basic security procedures.
Businesses should establish a clear response plan for suspected fraud. If an unauthorized transaction occurs, the merchant should contact the bank or payment provider through verified channels and report the incident promptly. Records of messages, transaction IDs, phone numbers, and screenshots may support the investigation.
The Impact on Employment and Business Skills
Technology is changing the skills required to manage a small business. In addition to product knowledge and customer service, shopkeepers may need basic digital accounting, online marketing, cybersecurity awareness, and data management skills.
This does not mean that every business owner must become a technology expert. Instead, practical digital skills can help merchants make informed decisions and reduce dependence on others for routine tasks. Younger family members or employees may assist with digital systems, but business owners should still understand how their accounts and payment processes work.
Educational platforms and local training initiatives can support this transition through courses focused on digital finance, entrepreneurship, customer engagement, and online safety. Learning opportunities are particularly useful when they are presented in accessible language and include practical examples relevant to small businesses.
The Future of Digital Payments for Small Businesses
The future of digital payments is likely to involve greater integration between payment services, inventory management, billing, customer communication, and financial reporting. Small businesses may increasingly use connected tools that allow them to track sales, manage stock, generate invoices, and review performance from a single device.
Artificial intelligence and data analytics may also become more accessible to small businesses. These technologies could help merchants identify purchasing patterns, estimate demand, and automate certain administrative tasks. However, business owners should evaluate the reliability, cost, privacy implications, and security of any technology before adopting it.
The growth of digital commerce may also create opportunities for local businesses to sell through online marketplaces, social platforms, and direct ordering systems. This expansion can increase reach, but it may require better packaging, delivery coordination, customer support, and return management.
The most sustainable approach is likely to combine digital convenience with personal service. Local businesses often succeed because customers value familiarity, trust, and community relationships. Technology should support these strengths rather than eliminate them.
Conclusion
Digital payments are changing small shops by improving transaction convenience, supporting electronic records, expanding customer options, and creating opportunities for business growth. QR codes, mobile applications, digital banking, and online marketing are helping local businesses participate in an increasingly connected economy.
At the same time, digital adoption brings challenges related to cybersecurity, technical reliability, transaction costs, financial management, and digital literacy. Small business owners need practical training and reliable support to use technology safely and effectively.
The future of local commerce will not depend only on whether a shop accepts digital payments. It will also depend on how responsibly the business manages customer information, maintains accurate records, responds to payment problems, and combines technology with quality service. When adopted thoughtfully, digital payments can become more than a payment method. They can serve as a foundation for stronger financial management, improved customer experiences, and sustainable growth for small businesses.
You may be interested
Celebrity Branding: How Public Figures Build Businesses Beyond Films
Anshika Jain - Sep 18, 2026The role of celebrities has changed significantly in the modern business environment. Actors, musicians, athletes, television personalities, and digital creators are no longer associated only with entertainment…
Electric Vehicles and Battery Recycling: The Next Challenge for Clean Transportation
Anshika Jain - Sep 18, 2026Electric vehicles (EVs) are transforming the transportation industry by offering an alternative to conventional vehicles powered by petrol and diesel. Governments, automobile manufacturers, technology companies, and consumers…
Green Startups: How Businesses Are Responding to Environmental Challenges
Anshika Jain - Sep 18, 2026Environmental challenges are influencing the way businesses operate, innovate, and plan for the future. Climate change, increasing pollution, resource shortages, waste generation, and the overuse of non-renewable…
Most from this category
Cybercriminals and Fake Online Platforms: How Users Are Being Tricked by Trusted Websites
Anshika Jain - Sep 17, 2026
The Rise of Citizen Journalism: When Ordinary People Become the First Source of Breaking News
Anshika Jain - Sep 17, 2026
India’s Startup Ecosystem: Why Tier-2 and Tier-3 Cities Matter
Anshika Jain - Sep 18, 2026Cybercriminals and Fake Online Platforms: How Users Are Being Tricked by Trusted Websites
Anshika Jain - Sep 17, 2026