
From Cash to QR Codes: How Everyday Payments Are Changing


The way people pay for everyday goods and services is changing faster than ever before. For decades, cash was the most familiar form of payment for everything from buying groceries and paying for transportation to settling restaurant bills and purchasing small items from local shops. Coins and banknotes were accepted almost everywhere, and carrying a wallet filled with cash was a normal part of daily life.
Today, that routine is changing. Smartphones, mobile banking, digital wallets, contactless cards, and QR codes have transformed the payment experience. A customer can purchase a cup of tea, pay a utility bill, transfer money to a friend, or complete a large transaction without physically exchanging cash. In many places, scanning a QR code has become as ordinary as handing over a banknote.
The growth of digital payments is not simply a technological change. It represents a broader transformation in how individuals, businesses, banks, and governments interact with money. Payments are becoming faster, more connected, and increasingly integrated into digital platforms. At the same time, the shift creates new questions about cybersecurity, privacy, financial inclusion, digital literacy, and access to technology.
The movement from cash to QR codes therefore reflects more than a change in payment methods. It is part of a larger transition toward a digital financial ecosystem in which smartphones and internet connectivity are becoming central to everyday economic activity.
The Traditional Role of Cash
Cash has remained a fundamental payment method because it is simple, familiar, and widely accepted. A customer hands over physical money, the seller provides the product or service, and the transaction is completed immediately. No internet connection, smartphone, application, or banking account is necessarily required.
Cash also provides a degree of privacy because transactions do not automatically create a digital record in the same way electronic payments do. For people who are uncomfortable with technology or do not have access to reliable digital infrastructure, cash can remain particularly important.
Small businesses and informal workers have historically depended heavily on cash. Street vendors, local markets, small retailers, transport providers, and service workers often preferred cash because it was straightforward and immediately available.
However, cash also has limitations. Businesses must handle, count, store, and transport physical money. Customers need to carry sufficient cash and may need exact change. Cash can also be lost or stolen, and large amounts of physical currency can create additional security and management challenges.
These limitations have helped create opportunities for digital alternatives.
The Rise of Digital Payments
Digital payments allow money to move electronically between individuals, businesses, financial institutions, and payment platforms. Instead of exchanging physical currency, users authorise a transaction through a digital system.
The growth of smartphones has played a major role in this transformation. A device that was originally designed primarily for communication has become a banking tool, wallet, identification device, shopping platform, and payment instrument.
Mobile banking applications allow users to transfer funds, pay bills, check balances, and manage accounts from almost anywhere. Digital wallets allow customers to store payment information and complete transactions through their phones. Contactless cards provide another way to make payments without inserting or physically handing over a card.
Among these developments, QR codes have become particularly visible because they offer a relatively simple connection between physical businesses and digital payment systems.
Why QR Codes Became So Popular
A QR code, or Quick Response code, is a two-dimensional barcode that can store information and be scanned using a smartphone. In payment systems, QR codes can connect customers to a payment account, merchant profile, transaction amount, or payment request.
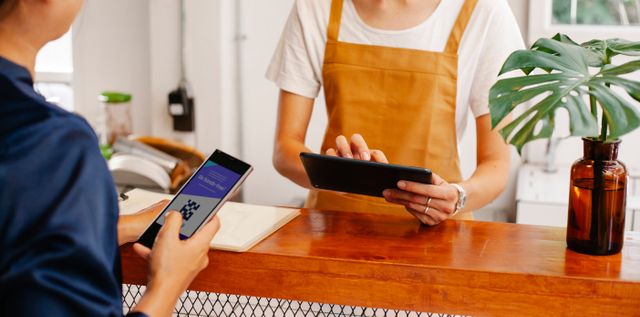
The basic process is straightforward. A customer opens a payment application, scans the merchant’s QR code, enters or confirms the amount, verifies the transaction, and receives confirmation. Instead of handling cash or physically exchanging a card, the transaction takes place digitally.
For small businesses, QR codes can be attractive because they require relatively little physical infrastructure. A merchant may display a printed code at a counter, on a sign, or even on a mobile device. This can make digital payments accessible to businesses that may not want to invest in more complex payment terminals.
For customers, QR codes offer convenience. A smartphone can effectively become a payment instrument, reducing the need to carry large amounts of cash.
India and the Expansion of QR-Based Payments
India has experienced a particularly significant transformation in digital payments. The expansion of smartphones, affordable mobile internet, banking access, and digital payment infrastructure has changed how many consumers and businesses conduct everyday transactions.
The Unified Payments Interface, commonly known as UPI, has played an important role in this transformation. UPI enables participating banks and payment applications to facilitate account-to-account transactions through a common digital infrastructure.
QR codes have helped make these transactions highly visible in everyday life. They can be found at grocery stores, restaurants, pharmacies, transportation services, educational institutions, local markets, and numerous small businesses.
The significance of this transformation extends beyond large cities. Digital payment systems have increasingly become part of everyday commerce in smaller towns and communities as well.
The result is a payment environment in which a person can move between cash, cards, mobile applications, and QR-based payments depending on the situation. Rather than completely replacing one payment method with another overnight, the financial ecosystem is becoming more diverse and interconnected.
How QR Payments Are Changing Small Businesses
The shift toward QR-based payments has had an important impact on small businesses. Traditionally, accepting digital payments could require card machines, merchant accounts, technical setup, and other infrastructure. QR-based systems can simplify this process.
A small retailer can display a QR code near the cash counter and allow customers to make electronic payments directly from their phones. This can reduce dependence on physical cash and make it easier for businesses to accept payments from customers who do not carry banknotes. Digital payment records can also provide businesses with a clearer view of incoming transactions. This can support accounting, reconciliation, and financial planning when the merchant maintains appropriate records.
However, digital payments do not eliminate challenges. Businesses must protect payment credentials, verify successful transactions, manage technical failures, and remain alert to fraudulent payment confirmations. The growing use of QR codes therefore creates both opportunities and new responsibilities for small businesses.
Convenience Is Driving Consumer Adoption
Convenience is one of the strongest reasons consumers adopt digital payments. People increasingly expect transactions to be quick and seamless. A customer purchasing a low-cost item does not necessarily want to search for exact change. A person splitting a restaurant bill may prefer to transfer money digitally rather than calculate and exchange cash.
Someone paying a utility bill may complete the transaction from home instead of visiting a physical office. Digital payments also integrate naturally with online shopping and app-based services. A single smartphone can connect banking, shopping, transportation, food delivery, entertainment, subscriptions, and financial services.
This integration is gradually changing expectations around payments. Consumers increasingly view payment as a background feature of a digital experience rather than a separate activity. The payment process is becoming less visible because it is increasingly integrated into the platforms people already use.
The Decline of Cash Does Not Mean the End of Cash
Although digital payments are expanding, cash remains important. Not everyone has equal access to smartphones, reliable internet connectivity, digital banking services, or the knowledge required to use payment applications.
Some people also prefer cash because they find it easier to understand and control their spending. Physical money can provide a clear sense of how much is available, while digital transactions may feel less tangible.
Technical problems can also interrupt digital payments. Poor connectivity, application failures, battery limitations, banking outages, or device problems can prevent a transaction from being completed.
For these reasons, the future of payments is unlikely to be defined simply by the complete disappearance of cash. Instead, different payment methods are likely to coexist, with consumers choosing between them according to their circumstances.
A truly inclusive payment ecosystem needs to accommodate both digitally connected users and people who continue to depend on physical currency.
The New Risks of Digital Payments
Digital payment systems provide convenience, but they also introduce new forms of risk. When money becomes digitally accessible, protecting accounts and payment credentials becomes extremely important.
Fraudsters may use fake payment links, fraudulent QR codes, impersonation messages, phishing websites, or social engineering techniques to trick users into authorising transactions.
One common misunderstanding is that receiving money requires entering a PIN. In legitimate payment systems, users generally should not need to provide confidential authentication credentials simply to receive funds. Fraudsters can exploit confusion about how digital payments work.
QR codes themselves are not automatically trustworthy. A code can potentially redirect users to a malicious website or connect them to an unintended payment destination. Customers should therefore verify the merchant and transaction details before confirming a payment.
Digital payment safety depends heavily on user awareness. Convenience should not eliminate verification.
Privacy and the Digital Payment Trail
The shift from cash to digital payments also changes the relationship between transactions and personal data.
Cash transactions generally do not create the same type of electronic record associated with digital payments. Digital transactions can generate information about payment amounts, dates, merchants, accounts, and other transaction details.
This information can be useful for consumers and businesses because it makes record-keeping easier. Customers can review transaction histories, while businesses can maintain electronic records of sales.
However, digital financial information also requires strong protection. Payment platforms, financial institutions, merchants, and users must take appropriate steps to protect sensitive information from unauthorised access and misuse.
As digital payments become more common, questions about data security and privacy will become increasingly important. A modern payment system must therefore focus not only on speed and convenience but also on responsible handling of financial information.
Digital Payments and Financial Inclusion
Digital payment systems can contribute to financial inclusion by making formal financial services easier to access. A person with a bank account and a compatible mobile device may be able to send and receive money without visiting a bank branch.
This can be particularly valuable for people living far from traditional financial infrastructure. Digital systems can make it easier to receive payments, transfer funds, pay bills, and participate in online commerce.
However, financial inclusion cannot be measured only by the availability of digital technology. Users also need affordable connectivity, accessible banking services, digital literacy, language support, consumer protection, and reliable infrastructure.
If digital payments become the only practical way to participate in everyday commerce, people who lack access to these resources could face greater exclusion.
The goal should therefore be digital inclusion rather than simply digital adoption.
The Role of Digital Literacy
As payment technology becomes more sophisticated, financial literacy and digital literacy are becoming closely connected.
People need to understand how digital payments work, how to verify transactions, how to protect authentication credentials, and how to recognise common fraud techniques.
Students and young adults are particularly important participants in this transition because they are often early adopters of new digital platforms. Educational institutions can help by teaching practical financial and digital safety concepts alongside traditional academic subjects.
Understanding how to make a digital payment is useful, but understanding how to make one safely is even more important.
Digital literacy should therefore include basic awareness of payment security, privacy, fraud prevention, and responsible financial behaviour.
How Businesses Are Adapting to a Cashless Environment
Businesses are increasingly designing their operations around digital payments. Online stores naturally depend on electronic transactions, but physical businesses are also adapting.
Restaurants may provide QR codes for ordering and payment. Retailers may integrate digital receipts with payment systems. Service providers may accept transfers rather than cash. Subscription businesses can automatically charge customers through digital payment arrangements.
This integration can reduce friction between purchasing and payment. A customer can discover a product, place an order, pay, receive confirmation, and track the transaction within a connected digital environment.
For businesses, digital payments can also support new financial services. Transaction histories may help eligible businesses understand their cash flow and manage financial operations more effectively.
However, businesses must ensure that convenience does not come at the expense of security. Staff training, transaction verification, data protection, and fraud awareness are becoming increasingly important components of modern commerce.
The Future of Everyday Payments
The next stage of payment technology is likely to involve even greater integration. QR codes may continue to coexist with contactless cards, mobile wallets, account-to-account payments, biometric authentication, and embedded payment systems.
The concept of embedded finance is particularly significant. Instead of opening a separate banking application, users may increasingly encounter payment functionality directly within shopping, transportation, communication, entertainment, and other digital services.
Wearable devices may also become payment tools, allowing people to authorise transactions through smartwatches and other connected devices. Biometric technologies could further simplify authentication, although they will also raise important questions about privacy and security.
Artificial intelligence may contribute to fraud detection by identifying unusual transaction patterns and potentially flagging suspicious activity. At the same time, criminals may use increasingly sophisticated technology to create more convincing scams.
The future of payments will therefore involve an ongoing balance between convenience, innovation, security, privacy, and accessibility.
What the Shift From Cash to QR Codes Really Means
The movement from cash to QR codes represents a deeper change in how society understands money. Money is becoming increasingly digital, mobile, programmable, and interconnected.
A physical banknote can be held, exchanged, and stored without requiring a network connection. A digital payment exists within a broader technological infrastructure involving banks, payment networks, applications, devices, security systems, and data.
This transformation changes not only how transactions happen but also how people interact with financial services. Payments are becoming integrated into everyday digital behaviour.
For consumers, this can mean greater convenience and faster transactions. For businesses, it can create new ways to manage payments and interact with customers. For financial institutions, it creates opportunities to develop more connected services.
At the same time, society must address the risks that accompany this transformation. Digital fraud, privacy concerns, technological dependence, and unequal access must remain part of the conversation.
Conclusion
The journey from cash to QR codes is one of the clearest examples of how technology is changing everyday life. Payments that once required physical money can now be completed within seconds using a smartphone. QR codes have made digital payments particularly visible by connecting physical shops and services with digital financial networks.
This transformation offers significant benefits, including convenience, faster transactions, easier record-keeping, and greater access to digital financial services. However, it also creates new responsibilities. Users need to understand payment security, businesses need to protect customer information, and financial systems need to remain accessible to people who may not be fully connected to digital infrastructure.
Cash is unlikely to disappear everywhere, and different payment methods will continue to coexist. The important change is that digital payments are becoming a normal part of everyday economic activity.
The future of payments will not be defined solely by whether people use cash, cards, or QR codes. It will be defined by how effectively technology can make financial transactions convenient while maintaining security, privacy, reliability, and inclusion. As money becomes increasingly digital, understanding how these systems work will become an essential part of modern digital literacy.
Online Internship with Certificate
You may be interested
The New Water Crisis: Why Groundwater Is Becoming a Major Concern
Anshika Jain - Sep 28, 2026Water is one of the most essential resources for human survival, economic development, and environmental stability. While rivers, lakes, and reservoirs often receive the most attention in…
Space Debris: Why Earth’s Orbit Is Becoming More Crowded
Anshika Jain - Sep 28, 2026Earth's orbit has become an increasingly important part of modern life. Satellites support communication, navigation, weather forecasting, disaster management, scientific research, and national security. From mobile communication…
Satellite Internet and Remote Communities: Can Connectivity Reach the Hardest Places?
Anshika Jain - Sep 28, 2026Internet connectivity has become an essential part of modern life, influencing how people learn, work, communicate, access healthcare, and participate in the digital economy. From online education…
Most from this category
Data Breaches and Consumers: What Happens After Personal Information Is Leaked?
Anshika Jain - Sep 25, 2026

From OTP Fraud to AI Voice Fraud: How Online Scams Are Evolving
Anshika Jain - Sep 28, 2026Data Breaches and Consumers: What Happens After Personal Information Is Leaked?
Anshika Jain - Sep 25, 2026